Britain to establish guaranteed lifetime retirement income as statutory default for private pensions
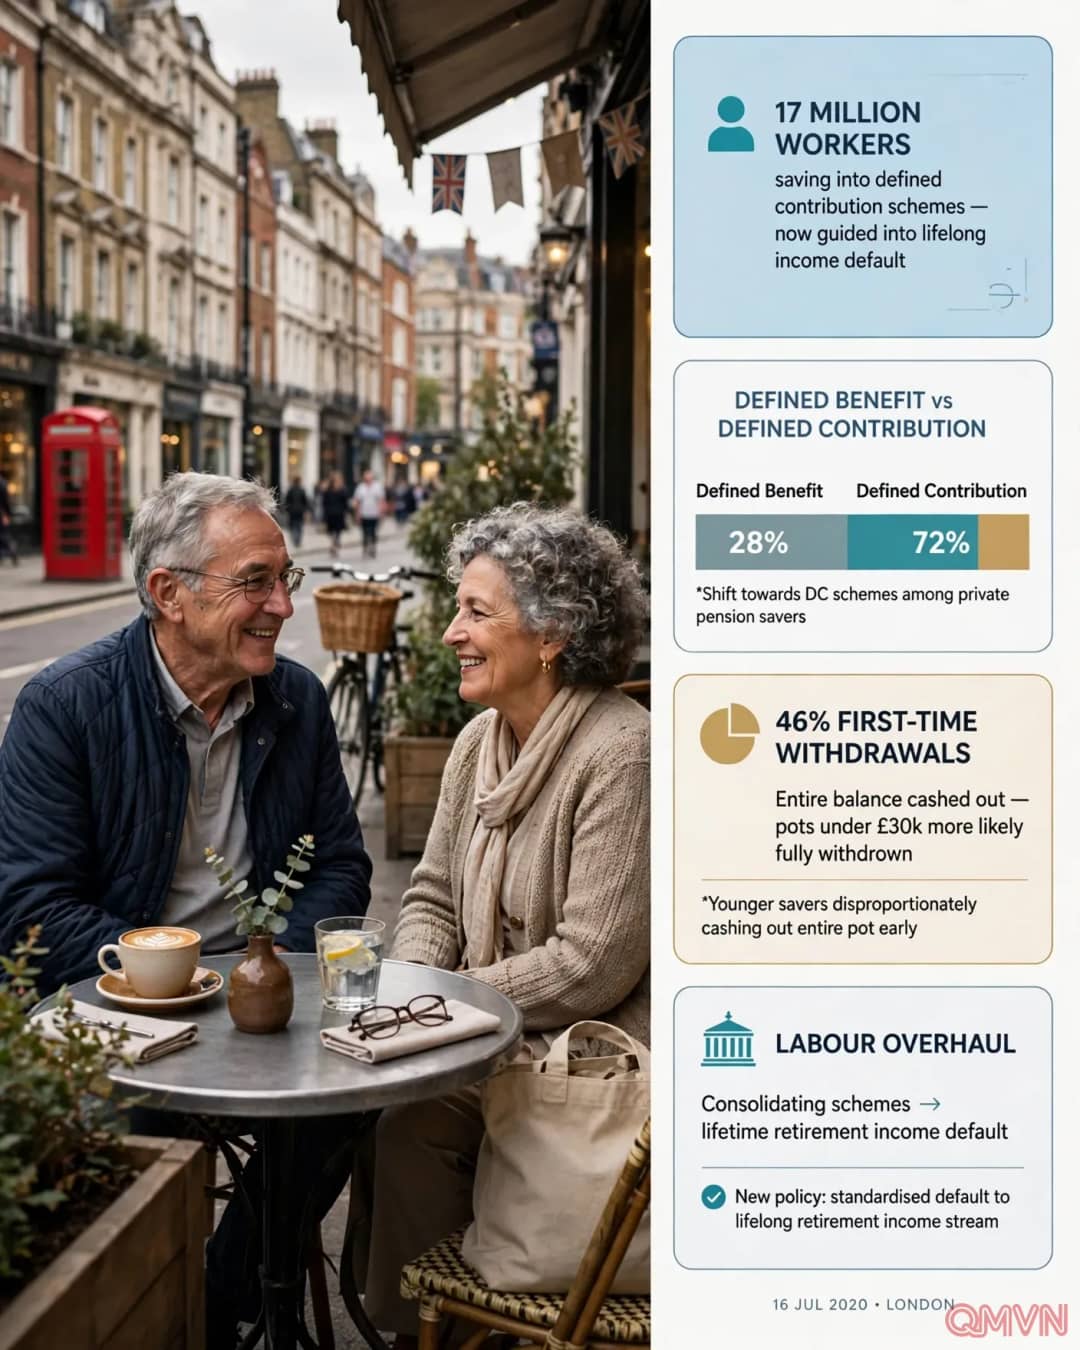
The British government on Tuesday, November 3, 2026, unveiled landmark structural pension reforms to designate a guaranteed lifetime income as the automatic default decumulation option for private sector employees, sparing millions of retirees from the financial complexities of managing individual pension pots. Under blueprints formulated by the Labour administration, roughly 17 million workers accumulating assets within defined contribution (DC) workplace schemes will be systematically guided into lifelong retirement income solutions unless they explicitly elect alternative arrangements. The initiative reintroduces core longevity protections characteristic of legacy defined benefit (DB) schemes—which largely vanished from the private corporate sector over the past three decades—while addressing alarming withdrawal trends and forthcoming inheritance tax mandates taking effect in 2027.
Edite QUANG MINH·2 min read · 3 min listen·3 November 2026, 08:32 EST·
AI-generated illustration
MAIN BODY
Guiding 17 million workers into lifetime streams and tackling lump-sum liquidation
The policy intervention focuses on defined contribution schemes, which aggregate employee and employer savings into a capital pot without guaranteeing lifetime cash flow, in contrast to legacy defined benefit arrangements. As life expectancy rises, unguided retirement decumulation has exposed substantial portions of the aging workforce to premature capital exhaustion.
Advertisement300 × 250
*
"While automatic enrolment has brought millions into workplace pensions, retirees are still largely left on their own to decide how to make their money last." — HM Government Department for Work and Pensions Policy Memorandum
*
Government data for the most recent financial year reveals that 46 per cent of initial pension pot accesses involved full cash liquidations, with balances below £30,000 overwhelmingly withdrawn in single lump sums. Furthermore, heightened speculation surrounding fiscal changes and the statutory incorporation of unused pension assets into inheritance tax regimes beginning in 2027 have accelerated early fund liquidations.
Approximately 17 million private sector defined contribution savers will default into guaranteed lifelong income pathways.
Official data reveals 46% of first-time pension pot withdrawals during the last financial year were total cash cash-outs.
The inclusion of unspent pension balances in statutory inheritance tax assessments from 2027 drives structural decumulation reform.
Labour’s structural consolidation agenda and balancing regulatory innovation
The initiative marks the latest milestone in the Labour administration’s broader overhaul of the domestic pensions architecture since assuming office in 2024. The macro-strategy focuses on aggregating fragmented workplace pools into massive consolidated funds capable of directing long-term capital toward productive domestic infrastructure and innovation assets.
*"Regulators should avoid creating a framework that limits future innovation in the retirement market while focusing on improving real-world outcomes for savers." — Kathryn Fleming, Head of Defined Contribution Consulting at Hymans Robertson*
Pensions consultancies and institutional market makers widely commended the removal of onerous financial decision-making burdens from vulnerable savers. However, sector analysts caution that regulatory supervisors must prevent rigid compliance mandates from stifling innovative retirement hybrid products that merge liquid flexibility with annuities.
The Labour government’s broader pension overhaul consolidates fragmented schemes to direct capital into productive assets.
Default mechanisms shield aging savers from costly asset misallocations and cognitive financial strain during retirement.
Industry consultancies urge regulatory authorities to maintain flexibility for bespoke hybrid decumulation innovations.
EVENT BACKGROUND
This major policy blueprint was presented in London on November 3, 2026, marking a critical transition in the United Kingdom’s post-industrial welfare regime following decades of demographic shifts and corporate pension restructuring. Across the late twentieth century, British private sector employment was anchored by defined benefit schemes that guaranteed a fixed, inflation-linked income until death; however, mounting corporate liabilities prompted private employers to almost universally abandon DB offerings in favor of defined contribution schemes, shifting longevity and investment risks entirely onto individual savers. Although the 2012 automatic enrolment mandate successfully incorporated millions into workplace accounts, the 2015 "Pension Freedoms" allowed individuals to withdraw pots entirely, generating a crisis of premature cash depletion. The fundamental crux of the challenge lies in balancing individual financial autonomy with systemic longevity protection: by introducing an automatic default pathway toward guaranteed lifetime annuities while retaining opt-out mechanisms, the government seeks to curb reckless lump-sum liquidations triggered by the 2027 inheritance tax changes without returning to rigid paternalistic constraints.
KEY LESSONS LEARNED
Behavioral default architectures (nudges) serve as indispensable public policy instruments to insulate consumers from complex financial mismanagement.
Mitigating societal longevity risk requires institutional mechanisms that convert volatile asset pots into guaranteed, lifelong income streams.
National pension consolidation must harmonize the double imperative of safeguarding retiree welfare while channeling long-term capital into productive economic assets.
Subscribe to the QMVN newsletter
A daily morning digest - only stories worth reading, no spam.