MAIN ARTICLE
A sharp improvement is not a full recovery
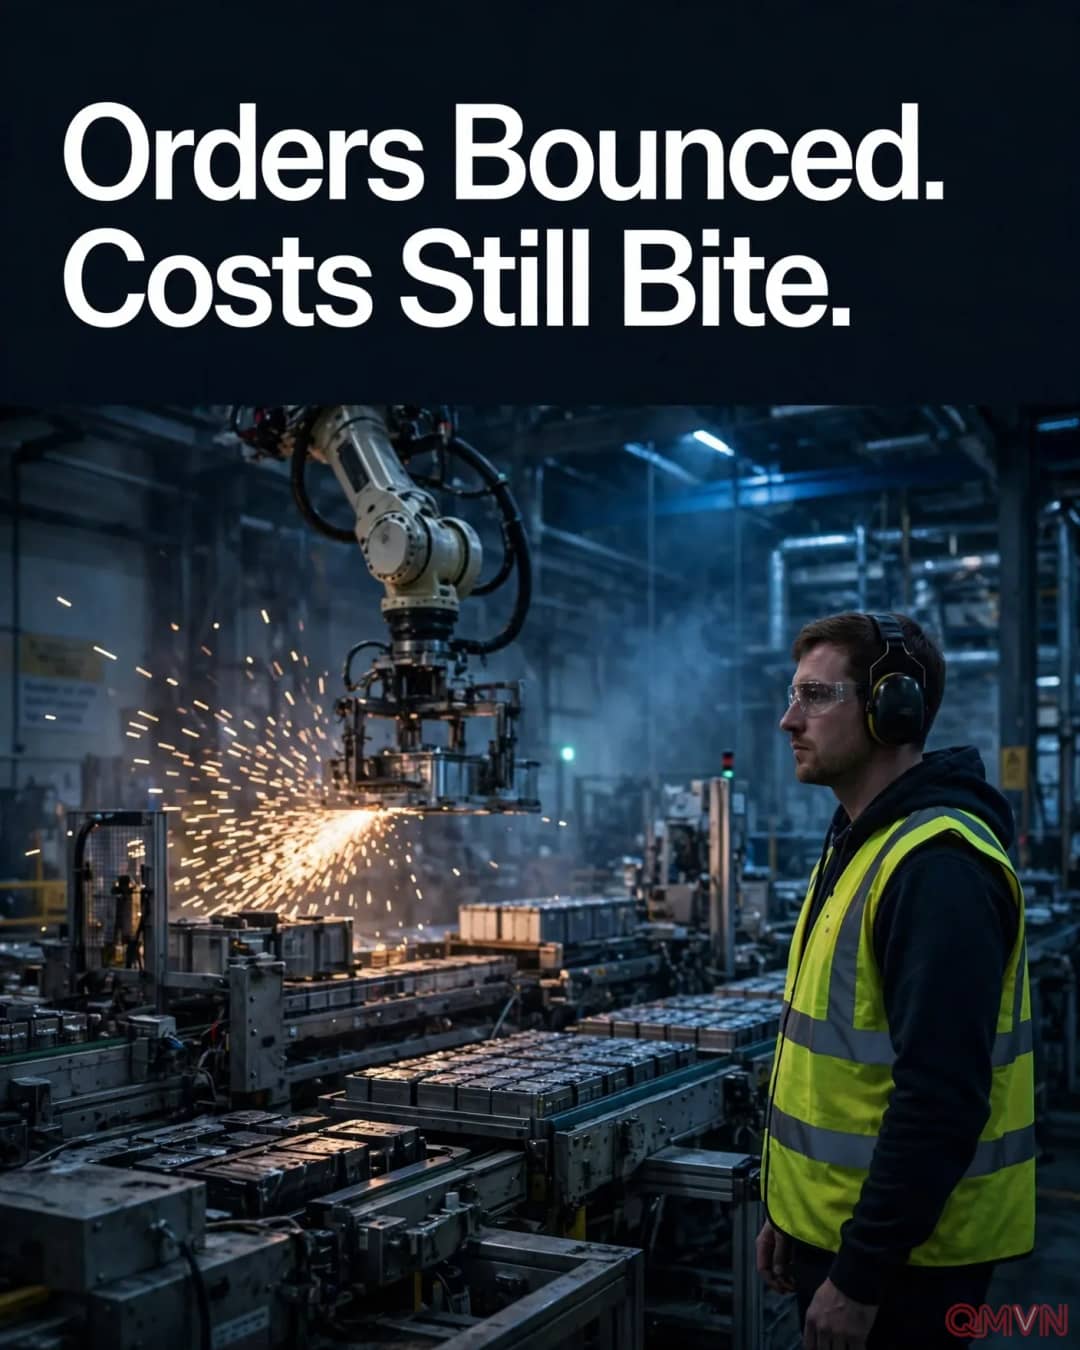
The headline survey reading made an unusually large monthly move. The balance for total orders rose by 20 points, from minus 32 in October to minus 12 in November, reaching its best level in two months. This is an indicator of the share of manufacturers judging their order books above or below normal, rather than a measurement showing that sales or production grew by 20%. Its negative sign is essential to the interpretation: the pressure on orders has eased, but it has not disappeared. The improvement was helped by aerospace and defence customers, whose demand patterns can differ considerably from those of consumer-facing factories.
The export-order balance also moved in a more encouraging direction, from minus 25 to minus 19. The CBI reported that both the overall and export order measures were broadly in line with long-run averages, providing perspective after October’s particularly weak outcome. However, a return toward the historical norm does not mean factories have recovered all the output, investment or confidence lost in previous years. For managers contemplating additional shifts or new machinery, a single better month is only one part of the business case. Repeat orders and predictable costs matter just as much.
Production expectations edge higher while costs persist
Manufacturers’ expectations for output in the next three months improved only modestly, to plus 1 from minus 1. That near-zero reading suggests companies anticipate broadly stable activity rather than a sudden surge. Forecast selling-price pressure eased as well: the balance for expected average prices slipped from plus 24 in October to plus 20.
This is a slower expected pace of price increases as measured by survey responses, not a prediction that prices will fall by four percent. It leaves firms trying to preserve margins while customers remain sensitive to costs.
The underlying squeeze is easy to understand. Energy-intensive production can become uncompetitive when power bills remain high even if new orders return. The CBI explicitly warned that persistent energy costs are reducing British manufacturers’ ability to compete. Its October quarterly survey had already described a long stretch of flat or declining output and difficult cost conditions, with many businesses questioning whether competitiveness would improve. The latest survey therefore records a potential turning point, not the disappearance of longstanding structural vulnerabilities.
The European market adds another uncertainty
Beyond factory gates, access to European demand is shaping investment calculations. The European Union’s proposed “Made in Europe” approach would link some procurement or industrial support to the origin of products and components. Because the United Kingdom is no longer an EU member, British manufacturers fear they could be left outside qualifying supply chains even when their factories are closely integrated with continental production. The exact treatment of British-made products depends on negotiations and the final design of the rules, so exclusion is a risk rather than a settled outcome.
The CBI has identified British participation in that framework as an urgent priority, alongside cooperation on emissions trading and potential relief from carbon-border burdens. Firms making cars, batteries, precision parts and complex industrial equipment need clarity well before contracts are signed. A rule that changes eligibility for subsidies or public-sector purchasing can influence where a multinational places its next plant. Equally, maintaining open access can support investment without requiring every component to be manufactured in one country.
What would turn a rebound into lasting momentum?
A credible recovery will need more than stronger demand in two specialist sectors. Economists will watch whether the orders balance continues moving toward positive territory, whether export orders improve across a wider set of industries, and whether output expectations translate into actual production. They will also look for falling energy cost burdens, steadier investment and improved productivity. A sustained change would appear across several successive surveys and in official manufacturing data, not merely in one month’s sentiment.
For policymakers, the November figures offer both encouragement and a warning. Aerospace and defence work can provide valuable industrial depth, but small suppliers across the country need competitive electricity, skilled workers and reliable access to buyers. For companies, rebuilding financial resilience may be wiser than treating a single improvement as permission to expand aggressively. The essential question is whether Britain can convert a tentative revival in orders into sustained employment, exports and industrial capability, while keeping the opportunities of European trade within reach.