MAIN ARTICLE
An authentic recovery, with uneven benefits
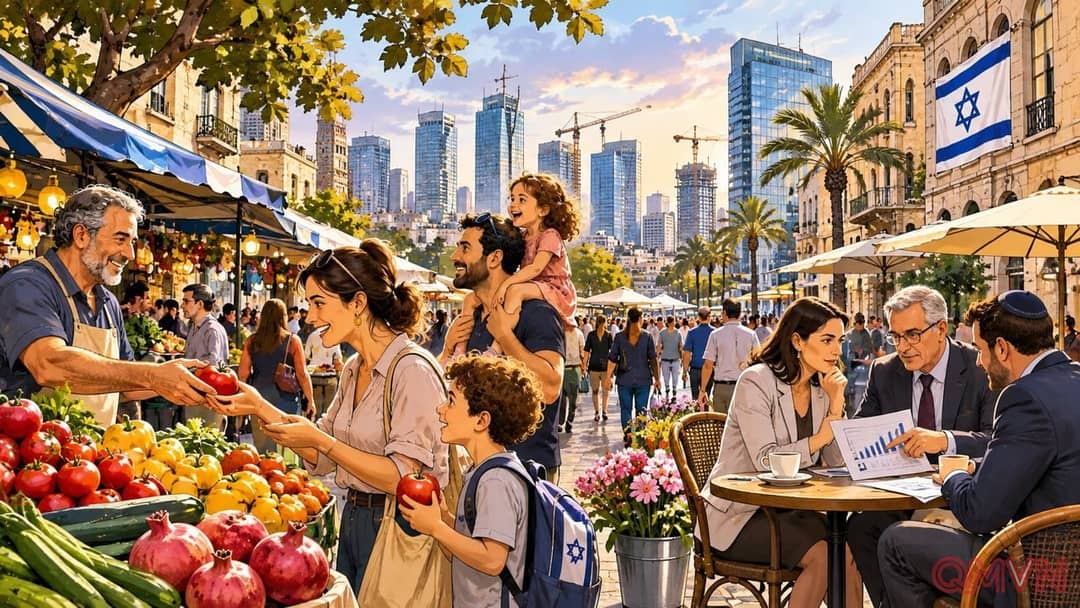
A busy produce market in Tel Aviv tells one side of Israel’s economic story: businesses and households continue adapting despite years of disrupted supply chains, security alerts and reservist mobilization. Technology services, exporters and banks have supported resilience. The other side is less visible in the streets: uneven household purchasing power and the difficulty of planning investments while regional risks remain elevated. Strong aggregate output cannot resolve those problems by itself.
The Bank of Israel’s October forecast projected overall GDP growth of 5.6% for 2026 and 7.5% for 2027. Its measure excluding production abroad—intended to better capture domestic activity—projected 3.4% and 5.1%, respectively. The striking difference is a reminder to distinguish impressive national accounts from the practical conditions facing employees, smaller firms and consumers.
Defense spending confronts the public balance sheet
War financing has drawn on tax revenues, borrowing and shifting spending priorities. The Wall Street Journal, citing the Bank of Israel, reported an estimated 405 billion shekels in conflict-related fiscal costs for 2023 through 2026. That burden includes costs extending beyond immediate weapons purchases, showing how a prolonged crisis can acquire a fiscal afterlife even when fighting subsides.