MAIN CONTENT
A strategic choice by Berlin
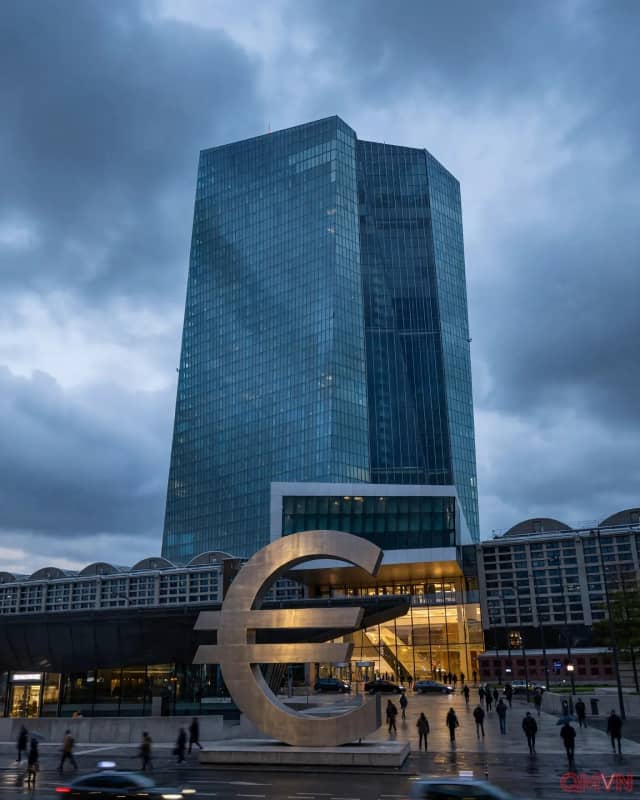
On Tuesday Germany’s Finance Ministry identified Markus Brunnermeier, a Princeton University professor, as its preferred candidate for a position on the ECB Executive Board, with a view to the chief economist job. People familiar with the discussions told Reuters that Berlin would support Pablo Hernández de Cos for president. That pairing matters because both jobs carry influence: the president represents and helps build consensus across the institution, while the chief economist contributes the analysis underpinning policy proposals.
The move also changes the landscape for Klaas Knot, the former Dutch central bank governor who had been competing with De Cos. Executive Board selection is not a straightforward contest of resumes. Governments consider economic expertise, political acceptability and representation across Europe. German support is consequential, but not equivalent to a final decision by the euro-area governments and the European Council.
Why De Cos is difficult to pigeonhole
De Cos built his career at Banco de España and served as its governor before becoming general manager of the Bank for International Settlements in July 2025. His record spans very different monetary conditions: when inflation was persistently weak, he supported negative rates and asset purchases; after Russia’s invasion of Ukraine contributed to a surge in prices, he also supported rapid tightening.
The pattern suggests attention to the economic evidence rather than automatic loyalty to a single camp.
That is why the familiar north-versus-south description is useful only up to a point. Southern European governments often worry about high borrowing costs and financial fragmentation, while northern policymakers have traditionally emphasized price stability and fiscal discipline. But ECB officials are legally expected to serve the euro area as a whole. De Cos’s ability to persuade colleagues may prove more decisive than any supposed national preference.
Inflation and sovereign debt complicate the handover
The leadership negotiations coincide with a difficult monetary backdrop. Reuters reports that renewed, war-related inflation has revived expectations of interest-rate increases, while France’s budget troubles have unsettled government-bond markets. Higher borrowing costs can curb inflation, but they can also intensify pressure on heavily indebted countries and businesses. The ECB must evaluate these risks without appearing to finance national governments or abandon its price-stability mandate.
The president cannot determine rates alone. Monetary decisions are taken by the Governing Council, comprising Executive Board members and euro-area national central bank governors. Reuters cited Mizuho economists who viewed a De Cos presidency as modestly more accommodative at the margin but stressed his consensus-building tendencies and the importance of the other appointments. Such assessments are forecasts, not commitments by the candidate.
A wider reshuffle, not a single appointment
Besides the presidency, the approaching vacancies create an opening for France, which is expected to seek another Executive Board seat when Isabel Schnabel departs. Reuters identified Laurence Boone and Agnès Bénassy-Quéré among potential French candidates, while noting interest in improving gender balance. Portfolio allocation, including responsibility for markets and bond operations, could therefore become part of the wider negotiation.
The procedural details matter. Under the European Union appointment framework, the European Council chooses Executive Board members following a recommendation and consultations with the European Parliament and the ECB Governing Council. The German proposal and reported support for De Cos are important political signals, but none removes the legal stages. For investors, the crucial question is not simply who receives the presidency but how the whole governing team interprets inflation, financial stability and the limits of intervention.