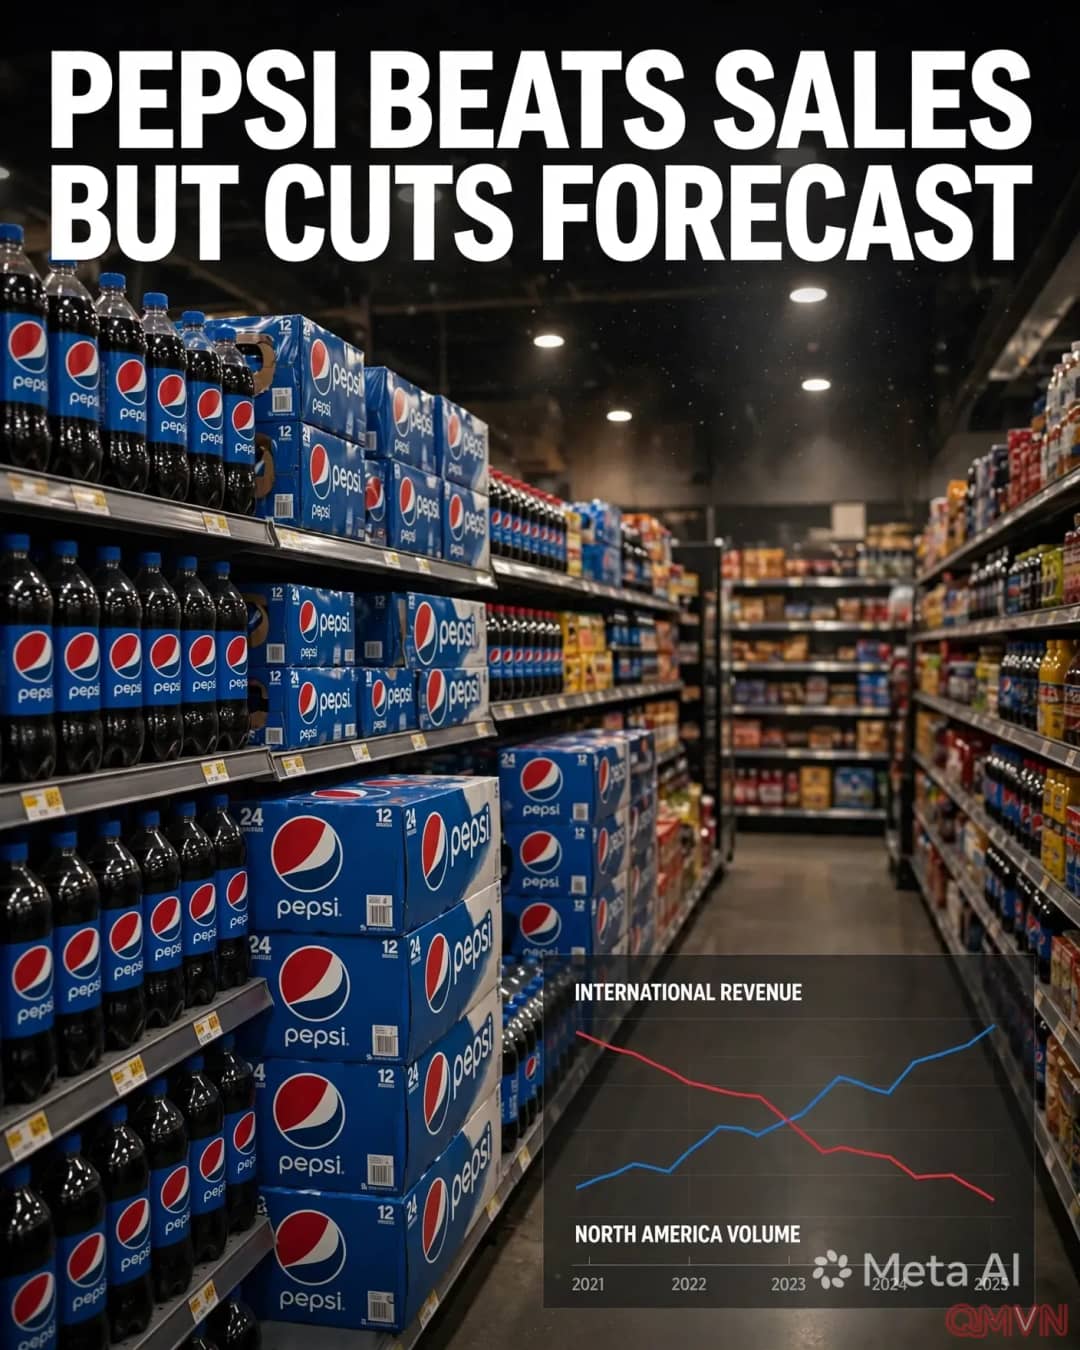
A Tale of Two Markets: International Expansion Versus Domestic Inertia
PepsiCo's third-quarter 2026 financial release presented financial analysts with a stark study in operational contrasts. On one hand, the enterprise generated net sales of $25.27 billion, representing a 5.6% advance year-over-year and beating consensus market forecasts of $24.96 billion. Adjusted earnings per share reached $2.34, outpacing the $2.29 estimated by Wall Street.
Growth was decisively propelled by overseas markets, which have accounted for 41% of consolidated net revenue so far this year. Sustained volume expansion across international operating segments served as a dependable stabilizer, cushioning the persistent weakness observed across North American divisions.
Our business in North America performed below our expectations and represents a meaningful opportunity for improvement.
Nonetheless, lingering domestic drag compelled leadership to lower full-year core earnings per share guidance to 2.5% to 3.5%, retreating from prior projections situated near the low end of the 5% to 7% bracket.