A bigger business does not necessarily earn better returns
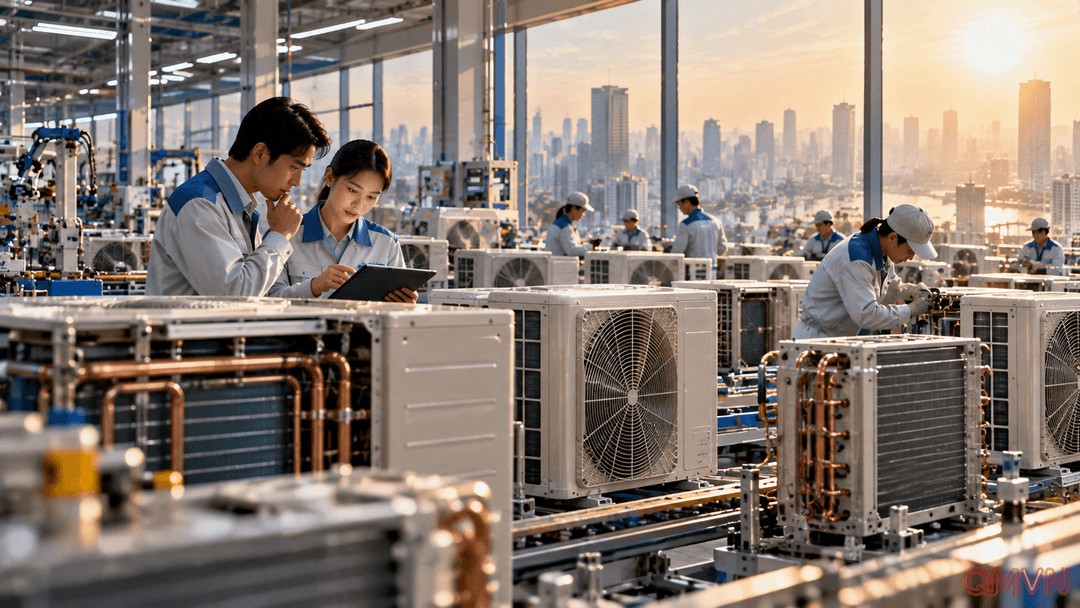
Longer and more intense summers are supporting air-conditioning demand in many markets. But as Nikkei Asia reported on October 2, investors are questioning whether Daikin’s growing asset base is producing enough profit. Factories, distribution infrastructure and acquired businesses can expand reach while absorbing capital that might otherwise be used more productively.
Daikin’s own financial disclosures show that sales for the fiscal year ended March 2026 reached about ¥5.015 trillion, up from ¥4.752 trillion a year earlier. Operating profit was about ¥415 billion, while return on equity (ROE) slipped from 9.7% to 9.1%. ROE had been 12.3% in fiscal 2022. The divergence illustrates why revenue gains alone cannot settle investors’ questions about how efficiently the company uses equity.
Why operational weaknesses matter
Comparisons with American rivals Carrier and Trane invite debate about margins, the business mix and capital structure. ROE is influenced by debt, share buybacks and accounting practices, so it cannot be treated as a perfect standalone measure of management quality.