Global financial markets face structural breaking point as unprecedented artificial intelligence boom begins to fracture
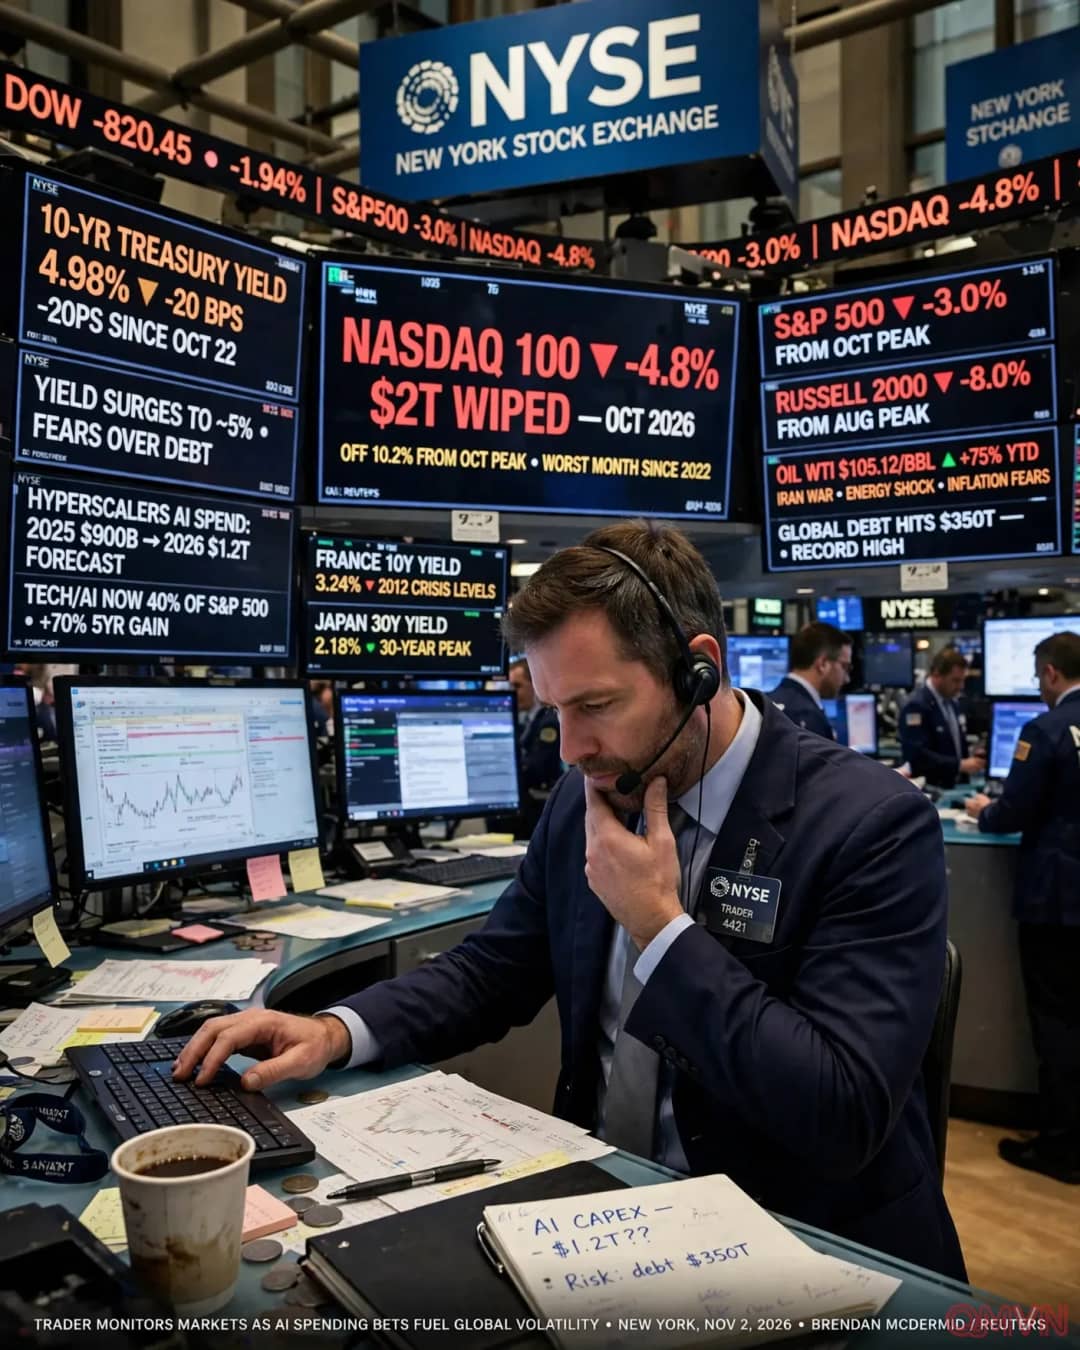
International financial markets are buckling under the compounding strains of expanding sovereign debt, regional military conflict, and trade instability, with early fractures now appearing within the multitrillion-dollar artificial intelligence investment surge that has served as the sole engine of global market optimism. With the protracted war involving Iran driving crude oil to $105 a barrel and reigniting domestic inflation across industrialized economies, central banks have been compelled to maintain borrowing benchmarks at multidecade highs, pushing the benchmark US 10-year Treasury yield toward the critical 5 per cent threshold. Following an abrupt $2 trillion market-value liquidation across the tech-heavy Nasdaq 100 in October triggered by mounting skepticism over AI capital returns, leading economists and regulatory veterans warn that debt-financed tech exuberance risks triggering a systemic economic contraction across a global economy already burdened by a record $350 trillion debt mountain.
Edite QUANG MINH·2 min read · 4 min listen·3 November 2026, 06:12 EST·
AI-generated illustration
MAIN BODY
Cracks in the hyperscaler capital surge and October’s $2 trillion market contraction
For two years, the colossal capital outlays executed by a handful of American technology hyperscalers—forecast by Danske Bank to reach $1.2 trillion in 2027 following an estimated $900 billion in 2026—acted as a macroeconomic shock absorber. However, October’s sharp market rotation erased more than $2 trillion from the Nasdaq 100 index as corporate balance sheets faced intense scrutiny over enterprise monetization timelines.
Advertisement300 × 250
*"Rising rates always seem to sniff out and expose the most vulnerable time after time; countries and businesses too exposed suffer the most." — Jim O’Neill, Former Chief Economist at Goldman Sachs and Former UK Treasury Minister*
The acute concentration of market leadership has introduced severe systemic vulnerability, with technology and artificial intelligence equities comprising over 40 per cent of the entire S&P 500 index. Credit default swap premiums insuring tech corporate debt spiked sharply in October, while proposed private data center projects struggled to secure debt financing amid high yields.
More than $2 trillion in market value evaporated from the Nasdaq 100 in October amid escalating capital expenditure scrutiny.
Hyperscaler capital investments are projected to reach $1.2 trillion in 2027, equivalent to all European corporate investment combined.
Tech and AI equities constitute over 40% of the S&P 500, creating an extremely narrow, vulnerable market leadership profile.
Multidecade sovereign bond yields and the exhaustion of state fiscal firepower
Financial stress signals are multiplying across jurisdictions untouched by the AI investment wave. Sovereign bond yields in France surged to levels last witnessed during the 2012 sovereign debt crisis amidst violent domestic protests, while Japanese government bond yields hit 30-year highs, forcing monetary authorities to accelerate rate hikes.
*"You have a buildup of leverage and AI companies that are relying a lot more on debt now to finance their ambitions; I also worry about the lack of fiscal firepower if we have another crisis because we’re just so strapped." — Sheila Bair, Former Chair of the US Federal Deposit Insurance Corporation (FDIC)*
According to the Institute of International Finance (IIF), aggregate global debt has expanded to an all-time record exceeding $350 trillion—nearly triple the size of worldwide GDP. Geopolitical strategists warn that heightened diplomatic fragmentation among Western allies eliminates the possibility of coordinated fiscal stimulus packages comparable to 2008, leaving institutions defenseless against simultaneous shocks.
Aggregate global debt reached a record $350 trillion, severely curtailing sovereign emergency response capabilities.
French and Japanese benchmark bond yields breached historic crisis highs under imported energy inflation pressures.
Diplomatic divisions prevent coordinated multilateral monetary and fiscal interventions in the event of a structural crisis.
EVENT BACKGROUND
This comprehensive financial assessment was published on November 3, 2026, as nationwide polling commenced for the United States midterm elections, reflecting acute vulnerability across the global economic architecture. Throughout 2025 and 2026, massive enterprise capital spending on generative artificial intelligence served as the primary pillar sustaining equity benchmarks, allowing markets to absorb persistent tariff escalations and interest rate pressures. However, the military conflict in the Middle East involving joint US-Israeli strikes on Iran in early 2026 severely disrupted maritime corridors in the Persian Gulf, driving Brent crude oil upward by 75% to $105 a barrel and embedding high inflation across North America and Europe. The fundamental crux of systemic fragility lies in the direct collision between astronomical corporate borrowing to construct speculative AI computing clusters and the physical reality of sovereign debt reaching $350 trillion: with central banks unable to cut interest rates without triggering currency devaluations and governments lacking budgetary reserves, any fracture in the AI investment thesis threatens to expose the underlying weakness of the global economy.
KEY LESSONS LEARNED
An equity market driven by an excessively narrow cohort of mega-cap technology firms creates severe systemic fragility.
Protracted high-interest-rate environments inexorably expose debt-fueled corporate capital expenditures to severe solvency tests.
National fiscal sustainability and budgetary discipline remain the indispensable insurance policy against compounded global macro shocks.
Subscribe to the QMVN newsletter
A daily morning digest - only stories worth reading, no spam.