Tripartite Regulatory Framework Targets Audit Disclaimers
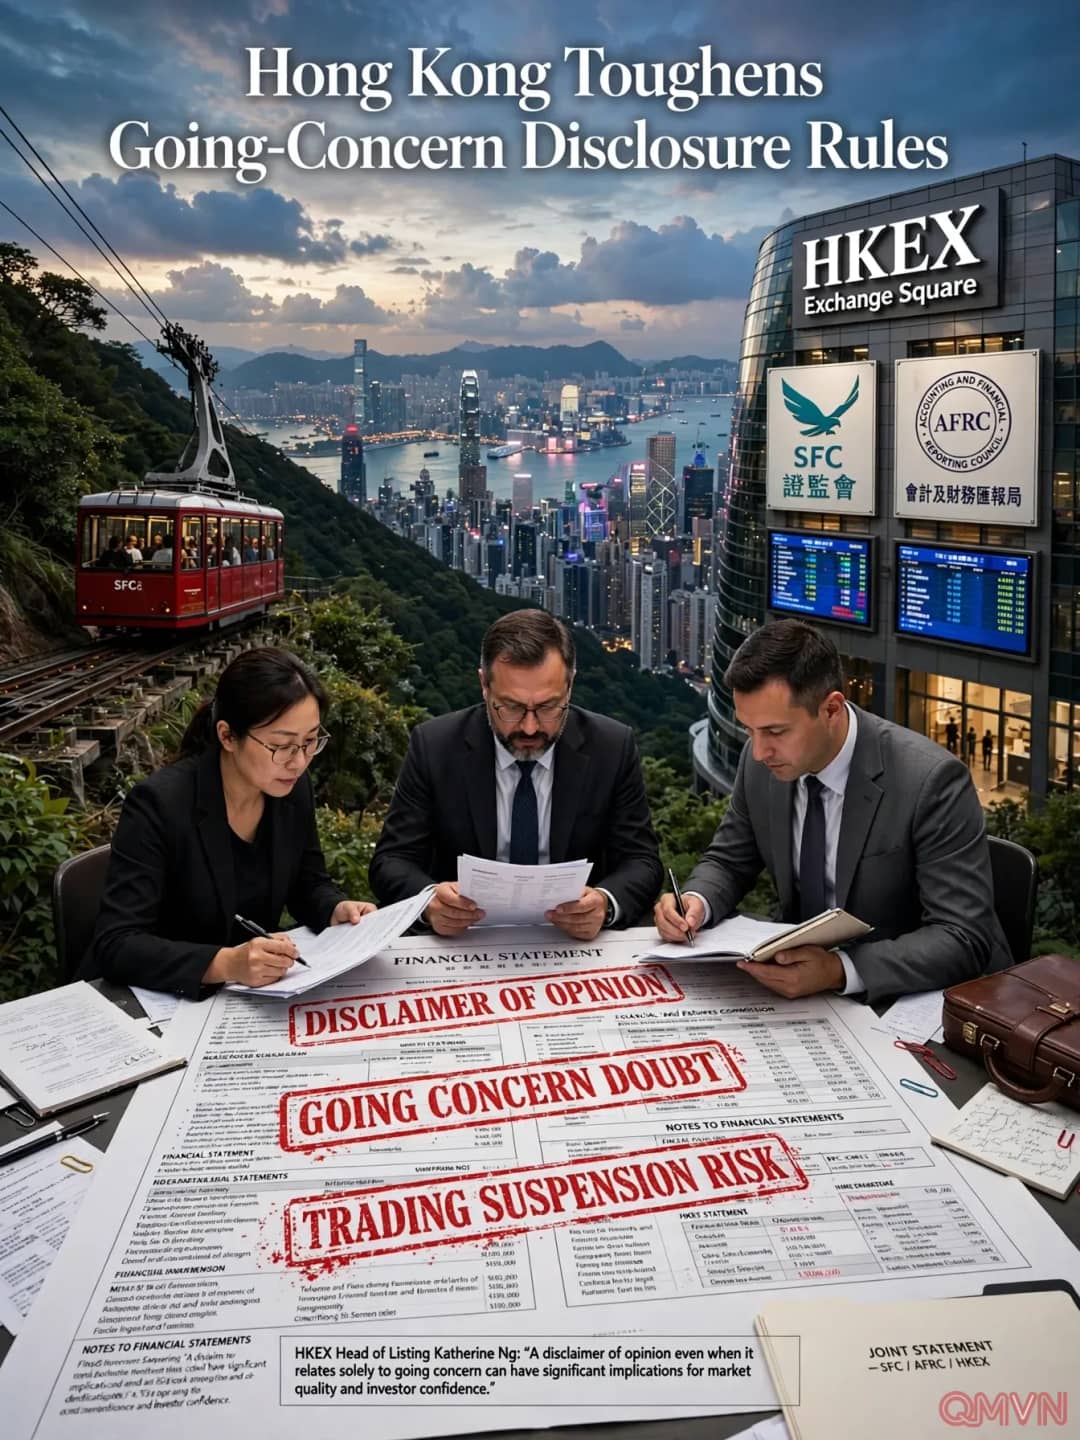
Hong Kong Exchanges and Clearing (HKEX) announced Thursday that it is collaborating with premier statutory watchdogs to elevate corporate financial disclosure standards, mandating that listed issuers and independent audit firms proactively resolve underlying going-concern ambiguities.
The Securities and Futures Commission (SFC), the Accounting and Financial Reporting Council (AFRC), and the Stock Exchange of Hong Kong issued a coordinated joint statement articulating supervisory expectations for corporate boards, audit committees, and professional accounting auditors.
A disclaimer of opinion, even when it relates solely to going concern, can have significant implications for market quality and investor confidence.
A disclaimer of opinion signifies that an auditor has been unable to obtain sufficient appropriate audit evidence to form an opinion on financial statements, casting profound doubt over the reliability and solvency of the reporting entity.