A $35 billion error
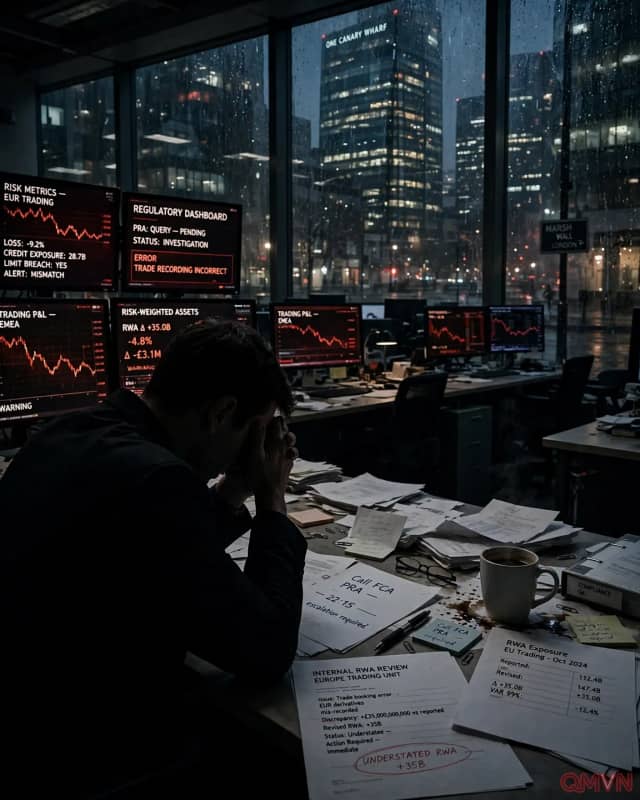
According to two people familiar with the matter, Citigroup incorrectly booked trades at a European subsidiary, leading it to underestimate its risk-weighted assets. One of them said the shortfall was about $35 billion at a trading unit in Europe.
Specifically, the Wall Street firm recorded trades at its UK securities unit using an internal model based on its own statistical assumptions. According to the sources, regulators had not approved the model for those types of transactions. Once the trades were recorded using a standard risk model, the value of risk-weighted assets rose significantly.
Citigroup’s response
In a statement to Reuters, Citigroup said it had identified and resolved an internal capital modelling issue at a European trading subsidiary this summer.
The subsidiary remained fully compliant with regulatory minimums throughout, with no impact on the holding company or main operating bank.
Citigroup said it had completed remedial actions and injected capital to immediately restore the subsidiary’s buffers.