MAIN STORY
A democratic verdict meets a reversal in market expectations
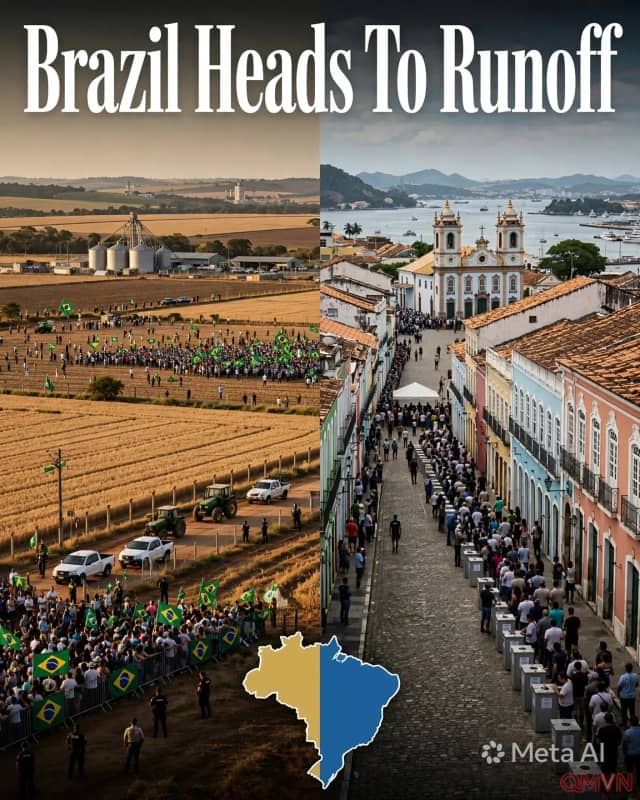
Brazil’s electoral authorities counted more than 64.2 million valid votes for Lula and nearly 59.9 million for Flávio Bolsonaro in the October 25 runoff. The narrow result offered a clear electoral winner without ending the country’s divisions over spending, taxation and economic opportunity.
Bolsonaro’s surprise first-round lead had encouraged investors to expect a more conservative fiscal policy. Brazilian equities finished the preceding Friday nearly 7% above their pre-first-round level, while the real was almost 5% stronger against the dollar. Monday’s initial overseas trading reflected a rapid unwinding of those positions, alongside declines in some long-dated international bonds.
Yet the distinction between indicative prices and completed sessions matters. A slide of more than 10% in currency futures and a roughly 26% premarket fall in EWZ did not mean that the entire local stock market had already closed at those losses. Volatility is an important signal, but its timing and trading venue shape what it actually tells us.
The debt arithmetic behind the selloff
Investors are less concerned with the identity of a victorious candidate than with the budget choices ahead. Brazilian public debt exceeds 82% of gross domestic product, and mandatory outlays, including pensions, narrow the government’s room to maneuver. Elevated borrowing costs can compound the fiscal problem as debt is refinanced.