CONTENT
Vital interdependence between physical tonnage and elite maritime services
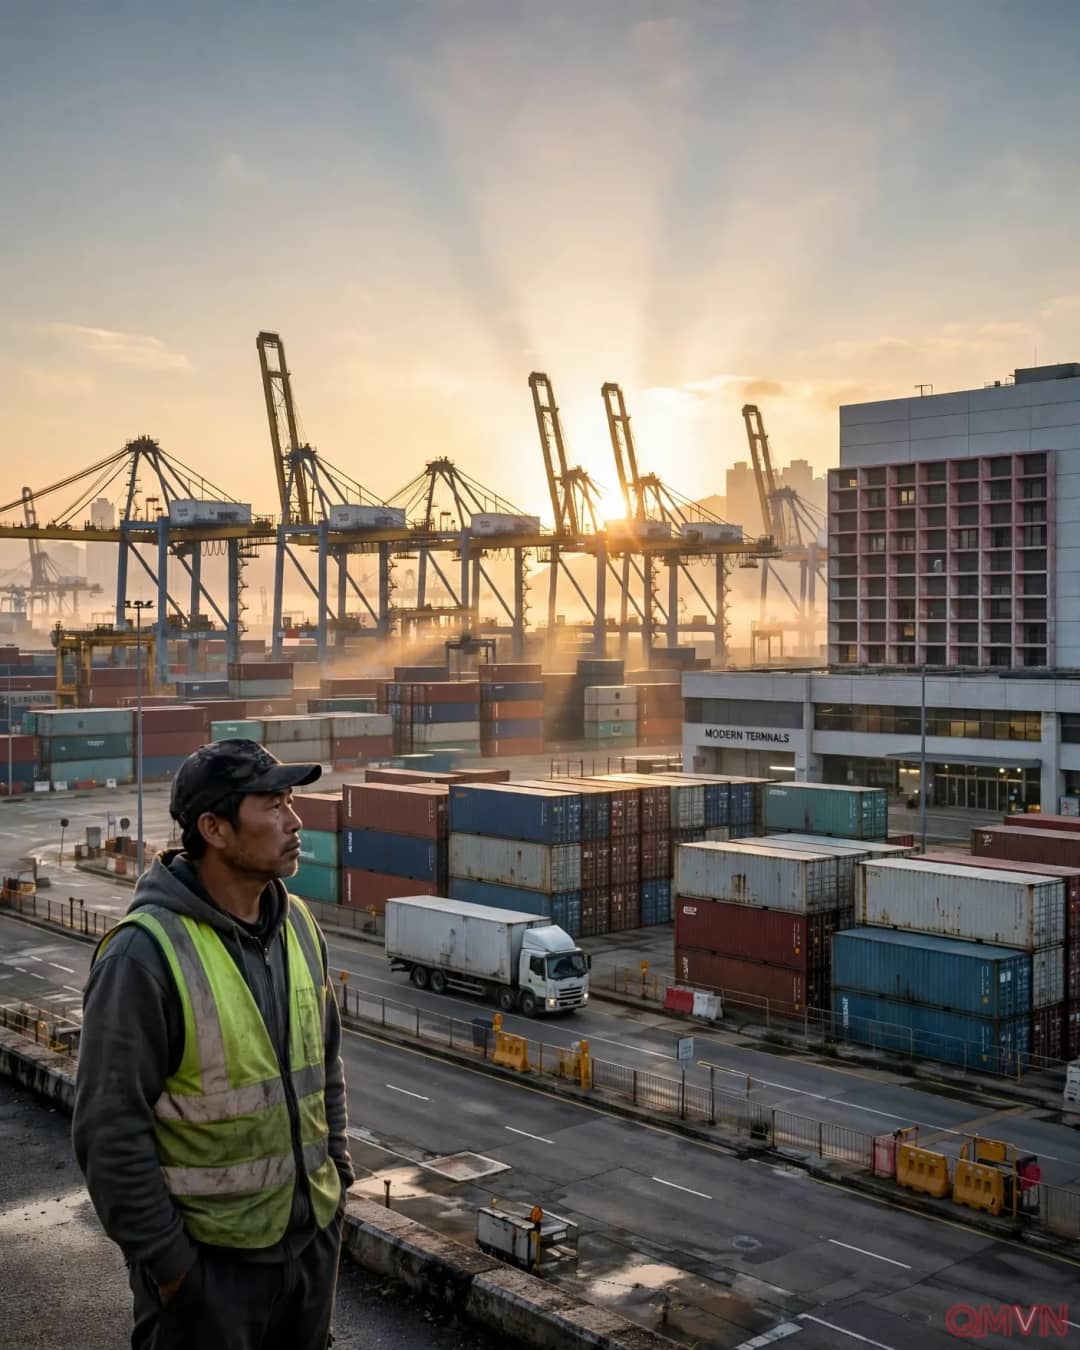
Hong Kong recorded a 5.1 percent annual contraction in port throughput in 2025, falling to 12.99 million TEUs despite a broad rebound in merchandise exports. In response to mounting public concerns regarding the city's status as an international maritime centre, policymakers have pivoted decisively toward value-added maritime commerce, prioritizing ship management, maritime law, and complex financial syndications.
Nevertheless, economic analysts emphasize that physical port operations generate the empirical data indispensable for underwriting marine risk, conducting ship surveys, and settling maritime claims. Dockside calls also drive lucrative commercial ventures such as green alternative fuel bunkering and emissions credit trading, which require consistent vessel traffic to build liquidity.
As maritime value compounds on operational scale, high-value maritime services cannot exist in a vacuum.
Embracing collaborative clustering within the Greater Bay Area
Reclaiming the dominant cargo volumes of prior decades is an unattainable objective, as mainland gateway ports have established direct manufacturing conduits. Consequently, Hong Kong's future prosperity depends on repositioning its deep-water terminals within the Greater Bay Area (GBA) multi-port collaborative network.
"The fate of Hong Kong's port is key to the competitiveness of the cluster." - David Yu Chak-wai
While automated terminals in Shenzhen and Guangzhou command vast industrial cargo hinterlands, Hong Kong possesses distinct institutional moats: a common law legal framework, free port status, zero capital controls, and sophisticated financial depth. Harmonizing feeder routes, green corridors, and digital customs manifests ensures that physical throughput across neighboring terminals directly enriches Hong Kong's professional services architecture.
Overcoming concession fragmentation through statutory port governance
Realizing this regional integration vision requires dismantling structural governance impediments rooted in Hong Kong's concession architecture:
The Kwai Tsing Container Terminals remain divided among five private corporate operators with leases extending until 2047.
The Marine Department currently lacks statutory authority to legally mandate terminal master planning or operational compliance.
Fragmented terminal ownership has hindered the deployment of unified smart logistics platforms and coordinated decarbonization investments.
Establishing a dedicated, centralized statutory port authority equipped with regulatory licensing levers is essential to orchestrate collective action, align capital investments, and negotiate strategic partnerships with state-owned mainland port groups.
BACKGROUND
This strategic inflection point originated with the massive development of modern mainland Chinese deep-water ports over the past two decades, which dismantled Hong Kong's historic monopoly as the sole transshipment conduit for southern manufacturing.
While state-owned mainland port champions expanded and Singapore consolidated its maritime ecosystem under the government-owned PSA, Hong Kong's Kwai Tsing terminals remained under private commercial ownership. As cargo handling volumes dropped below historical benchmarks, the government unveiled its first maritime five-year roadmap to reposition the city as an asset-light services powerhouse. However, escalating competition and the international transition toward green bunkering have demonstrated that high-value professional services wither without an active, modernized physical harbor, necessitating institutional reforms to restore regulatory leadership over terminal real estate.