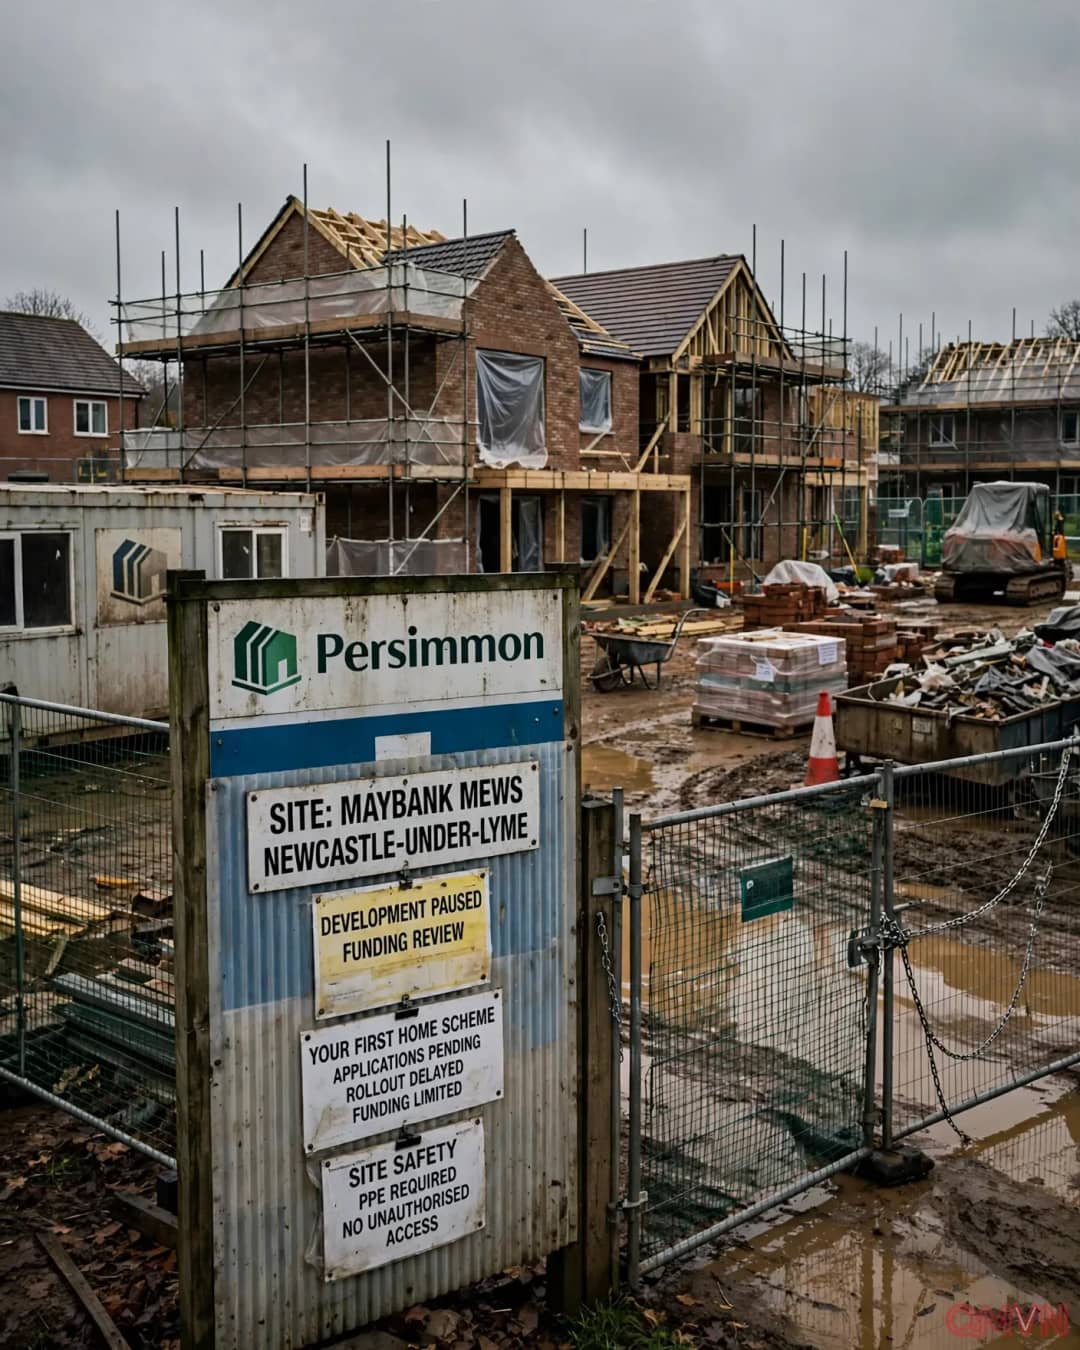
Sharp sectoral sell-off and the unwinding of speculative optimism
Immediately following the conclusion of Chancellor John Healey's fiscal address before the House of Commons, the benchmark UK homebuilders equity index plunged by more than 6%, completely eradicating the 9% valuation rebound accumulated since the policy was first signaled in September. Leading blue-chip developers including Barratt Redrow, Taylor Wimpey, and Persimmon each tumbled by approximately 7%, ranking among the steepest decliners across the broader pan-European STOXX 600 index.
“The biggest issue is more around the level of funding and the consequent duration of the scheme.” — Aynsley Lammin
Investor disappointment centered predominantly upon the modest £4.7 billion ($6.24 billion) capital allocation dedicated to state-backed equity lending. Industry analysts warned that such an allocation would likely exhaust itself within merely two operational cycles rather than providing a sustainable five-year programmatic framework, severely disincentivizing construction executives from committing capital to new land parcel acquisitions.
Rollout delays and the hazard of missed seasonal momentum
Compounding the funding constraint is the protracted administrative timeline governing the scheme's deployment. While the Treasury confirmed that the statutory framework would be introduced next spring, the disbursement of initial equity loans is scheduled to commence only in April 2027, almost certainly causing the industry to forfeit the pivotal spring property transaction window.