MAIN STORY
Relief is not a guarantee
Moody’s completed its October 23 review without lowering France’s Aa3 sovereign rating. That remains a high-grade assessment, but a negative outlook signals meaningful downside risk. Standard & Poor’s and Fitch already rate the country lower, making Moody’s decision a pause in the pressure rather than proof of a durable turnaround.
France’s finance ministry welcomed the result as recognition of its proposed budget. Moody’s, however, framed its assessment around assumptions: the deficit-reducing 2027 bill must pass and both borrowing costs and social tensions must moderate. Those are future conditions, not achievements already secured.
The 2027 budget becomes a political test
The draft budget seeks a deficit of 5% of GDP in 2027, compared with roughly 5.4% expected in 2026. Closing that gap requires choices about public services, taxes and spending that will affect households differently.
Lawmakers have already challenged or discarded several savings proposals, and opposition parties have limited incentive to embrace unpopular cuts before a presidential election.
The early parliamentary election of 2024 left no stable majority. The government must negotiate its fiscal legislation across competing factions while facing the possibility of a no-confidence vote. A sovereign rating therefore measures something beyond arithmetic: the state's ability to turn declared priorities into enforceable policy.
Bond markets deliver an early warning
French ten-year sovereign bond yields reached 5.14% during the week, their highest since 2002, according to Reuters. The spread over benchmark German debt, a measure of the extra compensation investors demand, also touched a roughly 15-year high. Higher yields can steadily increase the cost of financing deficits and replacing maturing debt.
Ratings do not by themselves determine the price of government debt. Investors also respond to economic growth, political uncertainty and the likelihood that promised budgets will be implemented. Avoiding a downgrade can calm immediate concern, but it does not automatically reverse a repricing of risk in the bond market.
Public anger and the problem of trust
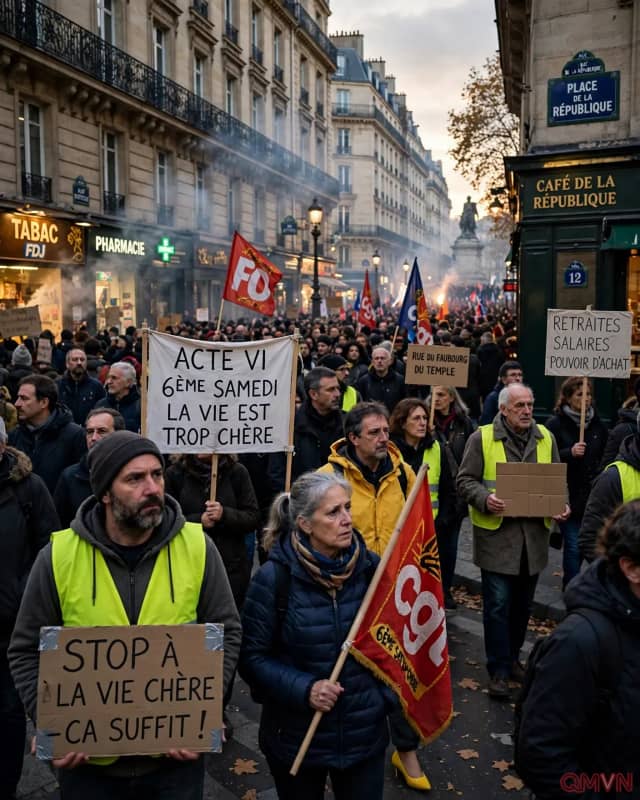
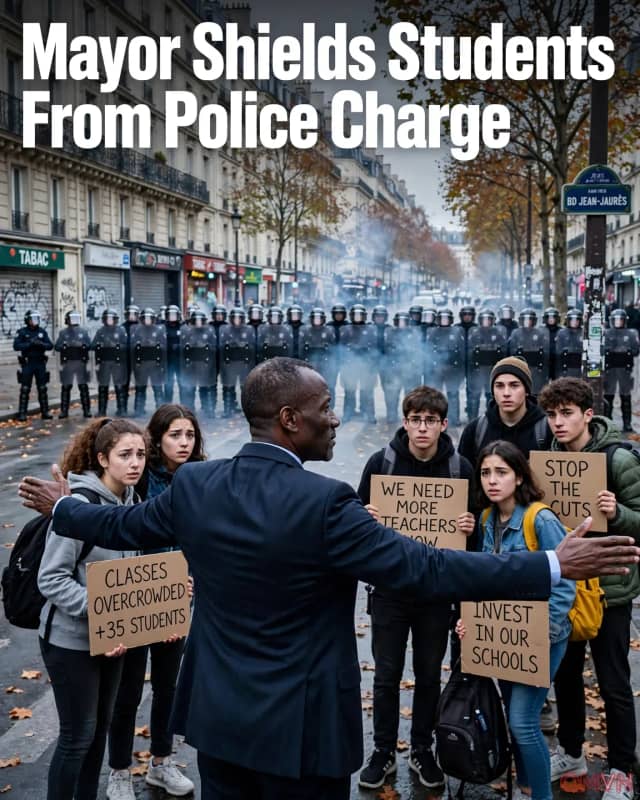
Demonstrations over living costs and the funding of schools have brought fiscal policy into the daily lives of French citizens. Recent protests have at times deteriorated into riots and vandalism, confronting authorities with the dual need to protect public safety and preserve peaceful dissent. Protesters as a whole should not be conflated with those responsible for violence.
Unrest may harden political positions, while abrupt austerity could intensify anger. The task is therefore not merely to identify budget savings but to explain them convincingly and distribute their burdens fairly. Investors will scrutinize the budget process as well as the presidential votes scheduled for April and May 2027.