MAIN ARTICLE
A growth narrative meets an affordability test
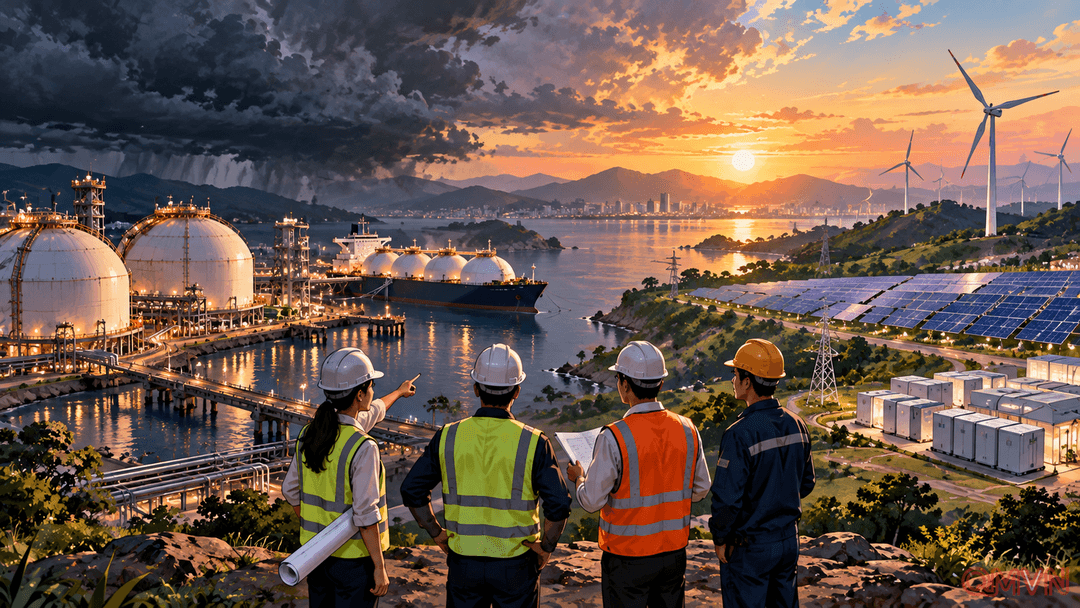
For more than a decade, South and Southeast Asia have appeared to be natural growth markets for seaborne gas. Mature domestic fields were declining, while cities, factories and power demand expanded. Developers planned import terminals, regasification equipment and power plants around that prospect. But LNG also requires energy-intensive processing, ships and complex supply arrangements. International price shocks can rapidly become domestic electricity costs, especially where utilities purchase significant volumes on the spot market.
Shell’s LNG Outlook 2026 puts global trade in 2025 at about 422 million tonnes and anticipates demand approaching 700 million tonnes annually in 2050. South and Southeast Asia could account for around 40% of worldwide imports by then, Shell estimates. Yet a projection is not a purchase commitment. The gap between scenarios built by suppliers and the contracts governments are willing to support is now the central story.
Four economies reconsider their options
Thailand makes that tension unusually visible. Natural gas still underpins much of its electricity supply, but a draft power strategy is moving toward a larger renewable share. Energy Minister Akanat Promphan has framed reduced exposure to costly, unpredictable spot LNG purchases as a priority.