Narrowing the capital gap
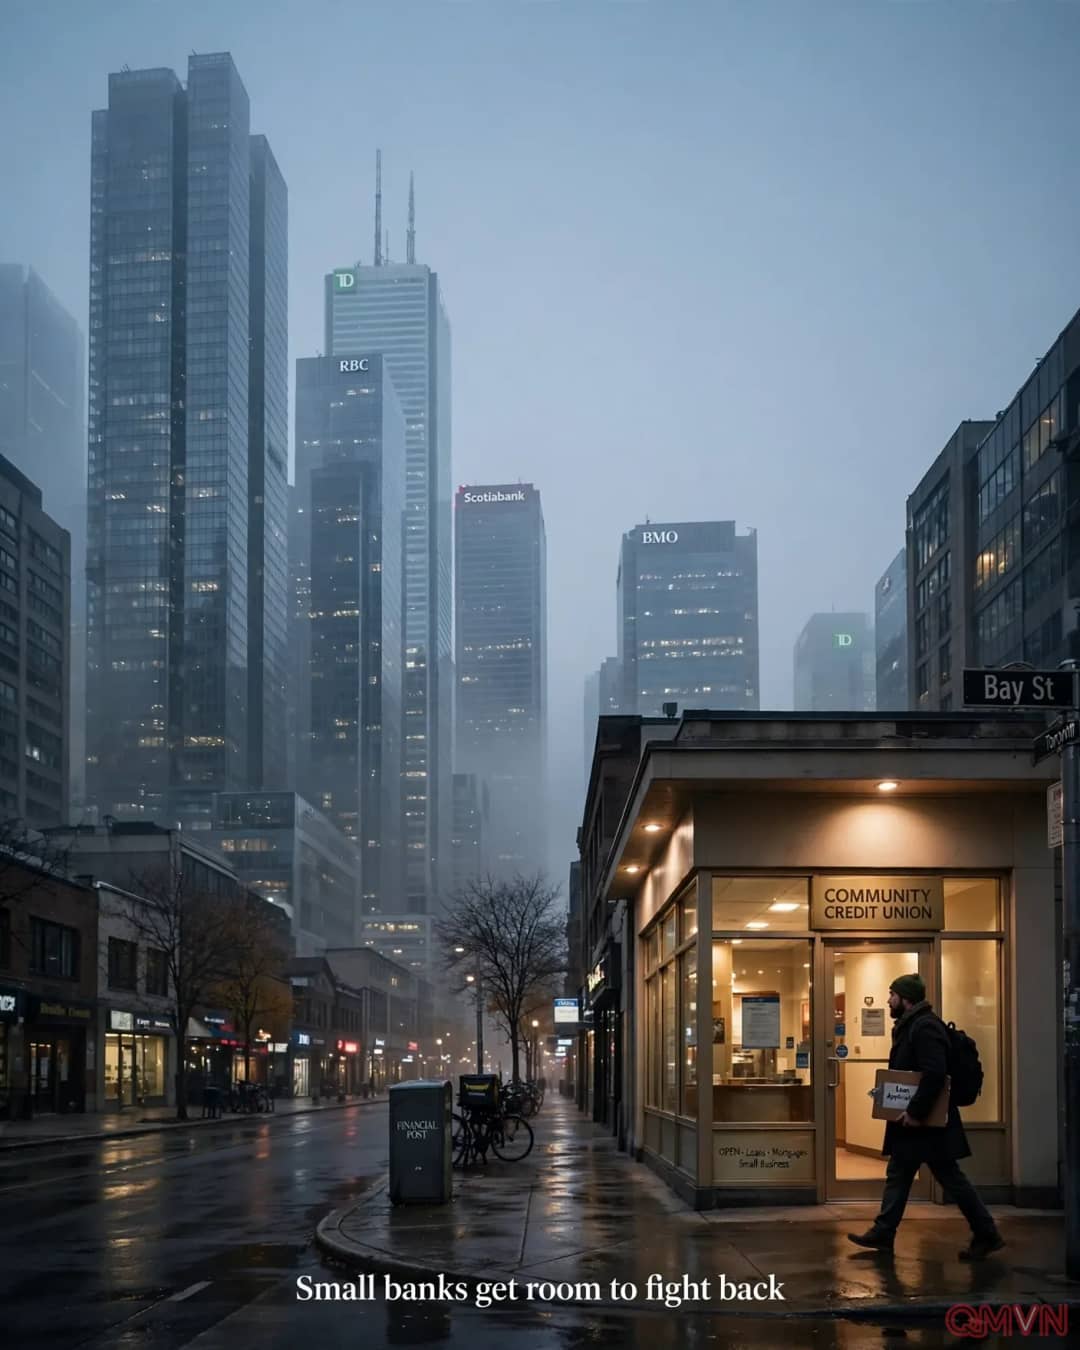
At the heart of the proposal is a sharp reduction in the difference between how much capital small and mid-sized banks must hold compared with large banks. OSFI said it has shrunk that gap by anywhere from 50% to two-thirds, depending on the category of loan, across residential mortgages, small and medium-sized business lending and corporate lending.
In practice, smaller banks would need to set aside less capital for low-risk mortgages. Loans worth less than half of a home's value would see their risk weight cut to 10% from 20%, while mortgages with a loan-to-value ratio of 50% to 60% would fall to 12.5% from 25%. After public consultation, the final changes are expected to take effect in late 2027 or early 2028.
A market dominated by six
Canada's six largest banks control more than 90% of banking assets, and the field of smaller rivals has thinned through consolidation. Canadian Western Bank, HSBC Canada and parts of Laurentian Bank have been absorbed by bigger lenders, while credit unions have merged among themselves to stay competitive.