MAIN CONTENT
A healthy bond market is not immune to stress
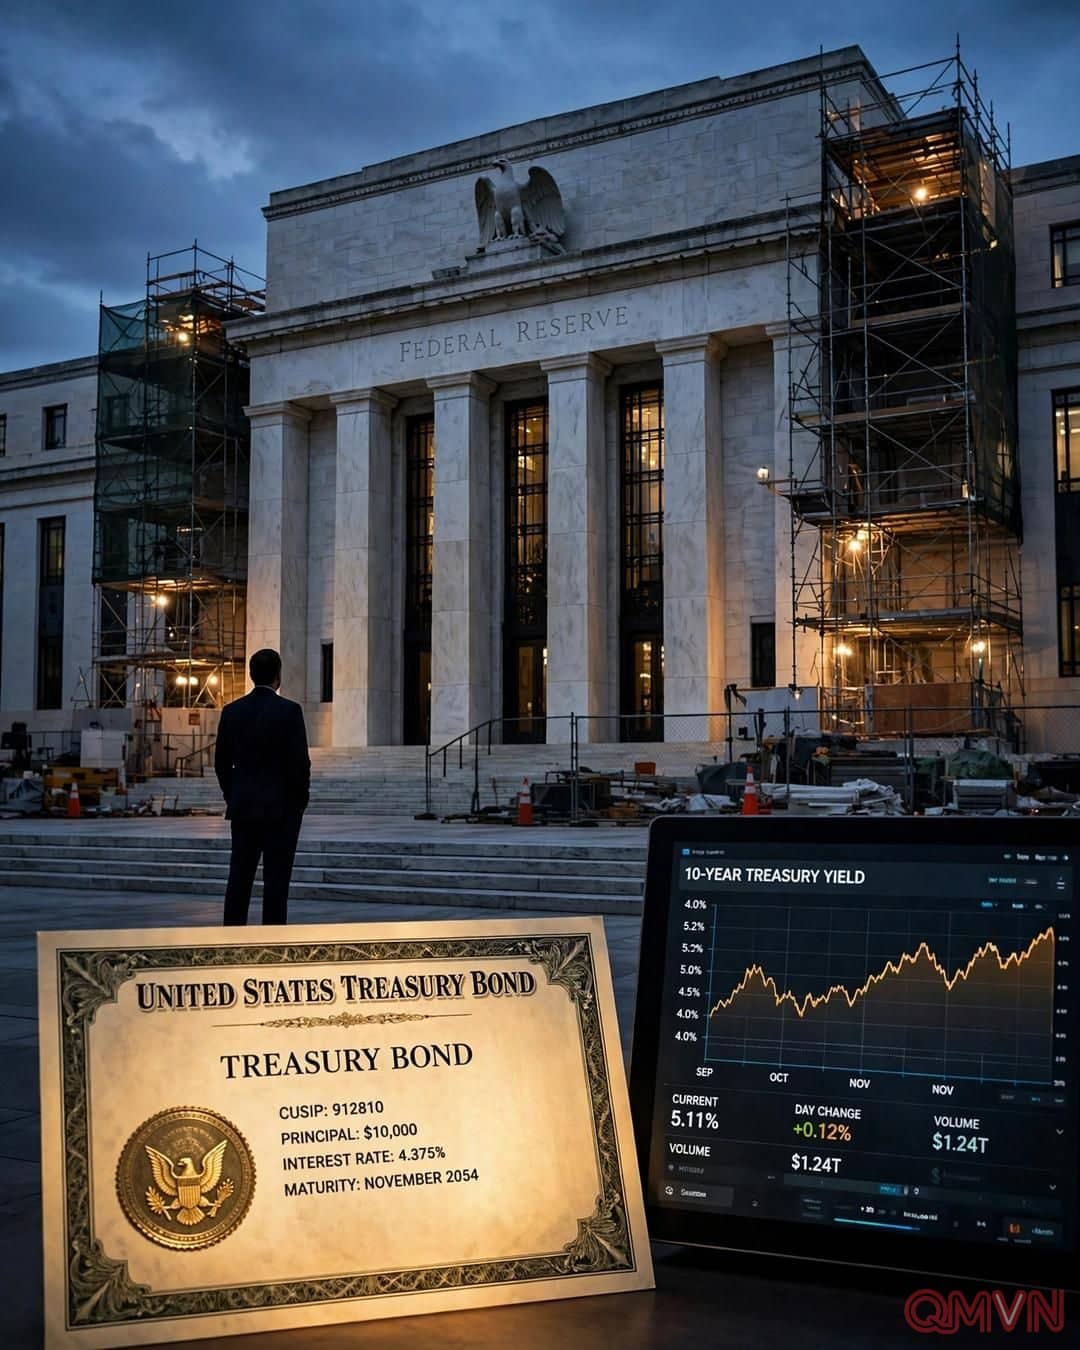
Logan described Treasury trading as functioning very well. Volatile yields alone, she cautioned, do not demonstrate a market breakdown: investors must be able to transact in ordinary sizes, within reasonable time frames and at manageable costs. A price moving sharply because buyers and sellers disagree is different from an inability to find buyers or execute trades. The Federal Reserve should distinguish the two before using public support.
The distinction matters globally. Treasury securities finance the U.S. government, serve as collateral across financial institutions and provide a reference yield for mortgages, corporate debt and numerous other assets. During the pandemic’s March 2020 rush for cash, widespread selling strained dealers’ capacity to intermediate. Logan warned that the market’s size has grown faster than those intermediaries’ balance sheets, leaving a vulnerability that can reappear during an unusually severe shock.
Why support should not become stimulus
The Federal Reserve traditionally bought assets to restore market functioning during crises that also justified easier monetary policy. That combination is harder today.