MAIN ARTICLE
Three indicators flash the same warning
China’s National Bureau of Statistics reported that October retail sales grew 0.4% year on year, down from 1.1% in September and below the 0.8% forecast in economists’ surveys. Industrial production grew 4.8%, easing from 5.5% and missing the 5.3% consensus. Together, the releases point to a softer start to the fourth quarter than policymakers had hoped.
Fixed-asset investment declined 8.1% in January–October, widening from a 7.2% drop in the first nine months. This is a cumulative ten-month comparison, not an October-only fall. The surveyed urban unemployment rate improved to 5.1% from 5.2%, though this measure alone cannot capture every pressure in a labor market that includes migrant and rural workers.
The property slump weighs on household confidence
Real-estate development investment fell 21.6% in the first ten months, compared with a 20.6% decline through September. The prolonged property downturn reaches well beyond developers: households whose savings are tied to homes become more cautious, while builders, suppliers and local governments confront weaker revenue and uncertain project pipelines.
Mortgage support, greater public borrowing capacity and faster project financing may soften the shock. But a lasting recovery depends on resolving unfinished developments, stabilizing buyer expectations and restoring confidence that families’ principal assets retain value. New construction alone cannot sustain demand while households remain worried about their financial futures.
A two-speed economy: advanced factories versus cautious shoppers
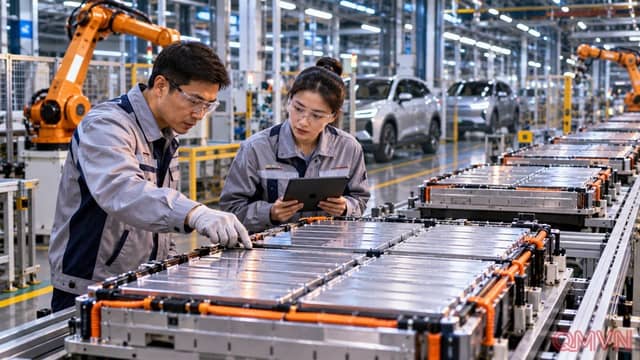
Not all production is weak. Official data showed high-tech manufacturing output rising 17.6% from a year earlier, while equipment manufacturing gained 10.6%.
Investment in intellectual-property products increased 9.2%. These pockets of dynamism demonstrate the appeal of China’s industrial upgrading strategy, even as housing and everyday consumption lag behind.
Exports of electronics and products tied to the global artificial-intelligence investment cycle provide another cushion. Yet that source of strength is exposed to trade restrictions, tariff disputes and changing overseas capital spending. The critical issue is whether technological success can ultimately raise employment quality, household incomes and domestic consumption rather than remain concentrated in selected export industries.
Why lower interest rates may not be enough
The People’s Bank of China has signaled caution about easing when demand for loans is already weak. Cheaper borrowing is of limited help if households doubt their income prospects and businesses see insufficient customers. Economists therefore increasingly discuss fiscal measures targeted at consumers, social services and the areas where spending support could produce the strongest effect.
Any response must also avoid creating another cycle of debt-financed projects with uncertain returns. Clearer property-market rules, stronger safety nets and credible local-government finances may matter as much as the headline size of a stimulus package. The Central Economic Work Conference, customarily held in December, will offer indications of Beijing’s priorities for 2027.
What the next data releases must show
Investors and families will watch year-end retail spending, housing transactions, local public expenditure and export orders for evidence of stabilization. One month cannot establish a permanent trend, but simultaneous disappointments in several key series suggest recent measures have not yet reached the broader economy at sufficient scale.
The statistics bureau described overall activity as stable and economic restructuring as ongoing, while acknowledging external uncertainty and imbalances between supply and demand. Those observations can coexist: new industries can grow impressively even as consumers hesitate. A convincing recovery will be one in which the distance between those two realities begins to narrow.